Mobile lending journey
Mobile lending journey
A resumable, mobile-first application: biometric capture, dynamic validation, and mid-session save that cuts abandonment.
Application capture, decisioning, underwriting, and disbursement, engineered against FCA Consumer Duty and PRA SS1/23 model-risk from week one.
One decision engine, one audit trail: the app borrowers apply in, the portal they service from, and the underwriter console.
A resumable, mobile-first application: biometric capture, dynamic validation, and mid-session save that cuts abandonment.
Statements, repayment schedules, payment-holiday requests, and arrears self-service, accessible for every customer.
Case management with full customer context, per-decision reason codes, and one-click FCA and PRA export.
Production lending outcomes, each figure sourced to a named client engagement.
Application capture, ML decisioning, underwriting, disbursement, and servicing, built, pen-tested, and model-risk-cleared in one 20-week programme.
Auto-approval on decisioned applications
- UK SME lender, up from 28%
Median quote-to-decision cycle
- UK SME lender, post-rebuild
Lending-journey NPS uplift
- Tier-2 UK retail bank, rolling
What lenders measure 12 months on.
Six structural defects every origination programme inherits, and the shape we ship in their place.
An event stream over the core and decision services, so capture, decisioning, and disbursement leave the overnight batch.
Resumable application with biometric capture and dynamic validation lifts completion before a credit search ever runs.
Faster Payments, SEPA, and card disbursement settle into one idempotent double-entry ledger, automatically reconciled.
Quarterly retrains behind continuous second-line monitoring replace the annual model ceremony, without the SS1/23 fear.
Every application scores inline with per-feature attribution and reason codes: a defensible decline, not a rule label.
Immutable reason codes and fair-value evidence stream continuously to your CloudTrail, Sentinel, or Chronicle SIEM.
A proven roadmap turning a regulated lending programme into bounded, audit-cleared stages.
Audit the funnel and FCA Consumer Duty, SS1/23, and Consumer Credit Act articles in play, then lock a costed plan.
Model specification, data flows, and a signed model card, cleared with second-line leads before decisioning ships.
Application, decisioning, underwriting, and disbursement progress in parallel pods behind feature flags, with CI gates from commit one.
Pen-test, accessibility audit, and the FCA notification pack, then pilot to a control cohort, clear review, and scale.
Regulated lending is the work we do most. Every reason below is one a reference client will confirm on a call.
The architect on your discovery call is the one in your FCA meeting. Consumer Duty and SS1/23 are design inputs, not gates.
Your AWS, Azure, or GCP account, your IAM, your KMS: no client data held, no shadow copies of credit files.
Model cards, reason-code mappings, and the Consumer Duty pack ship each sprint, not a scramble before a review.
A paid four-week diagnostic and a fixed-price build plan: no open-ended retainers, no scope that quietly expands.
Decisioning, underwriting, disbursement, servicing, and 24×7 SRE from one senior pod, no hand-off cliff.
We took a UK SME lender from a 9-day quote-to-fund to under 8 minutes, SS1/23 evidence cleared at first review.
Success stories
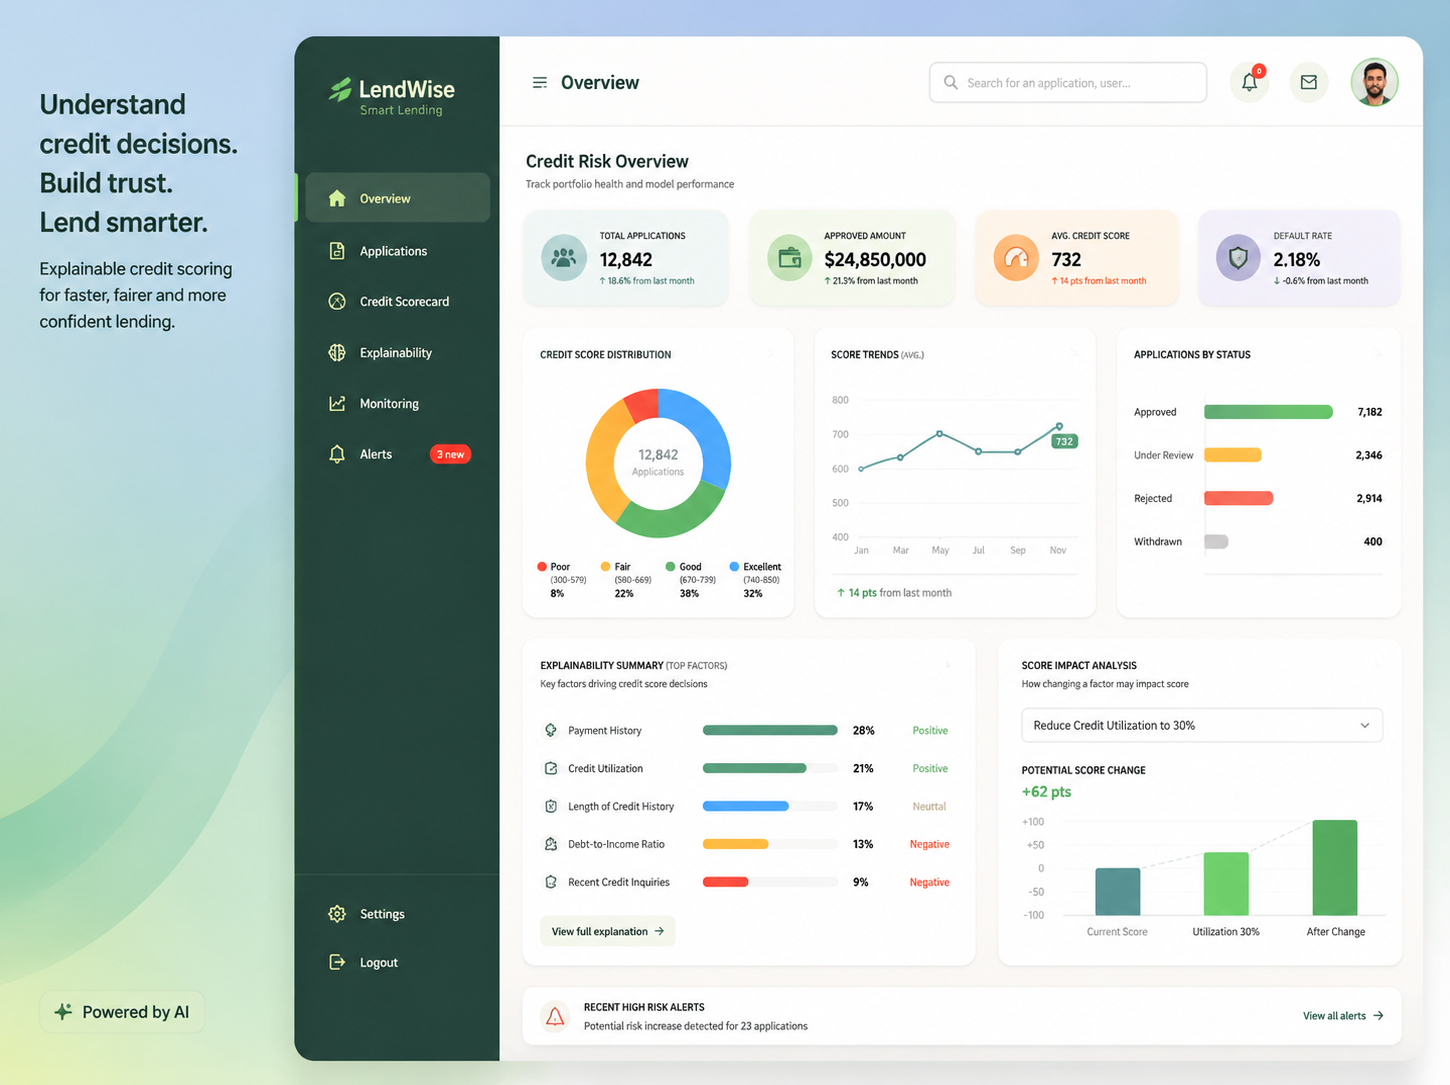
Lifted approval rates 31% at constant loss, every decision reason-coded for the FCA.
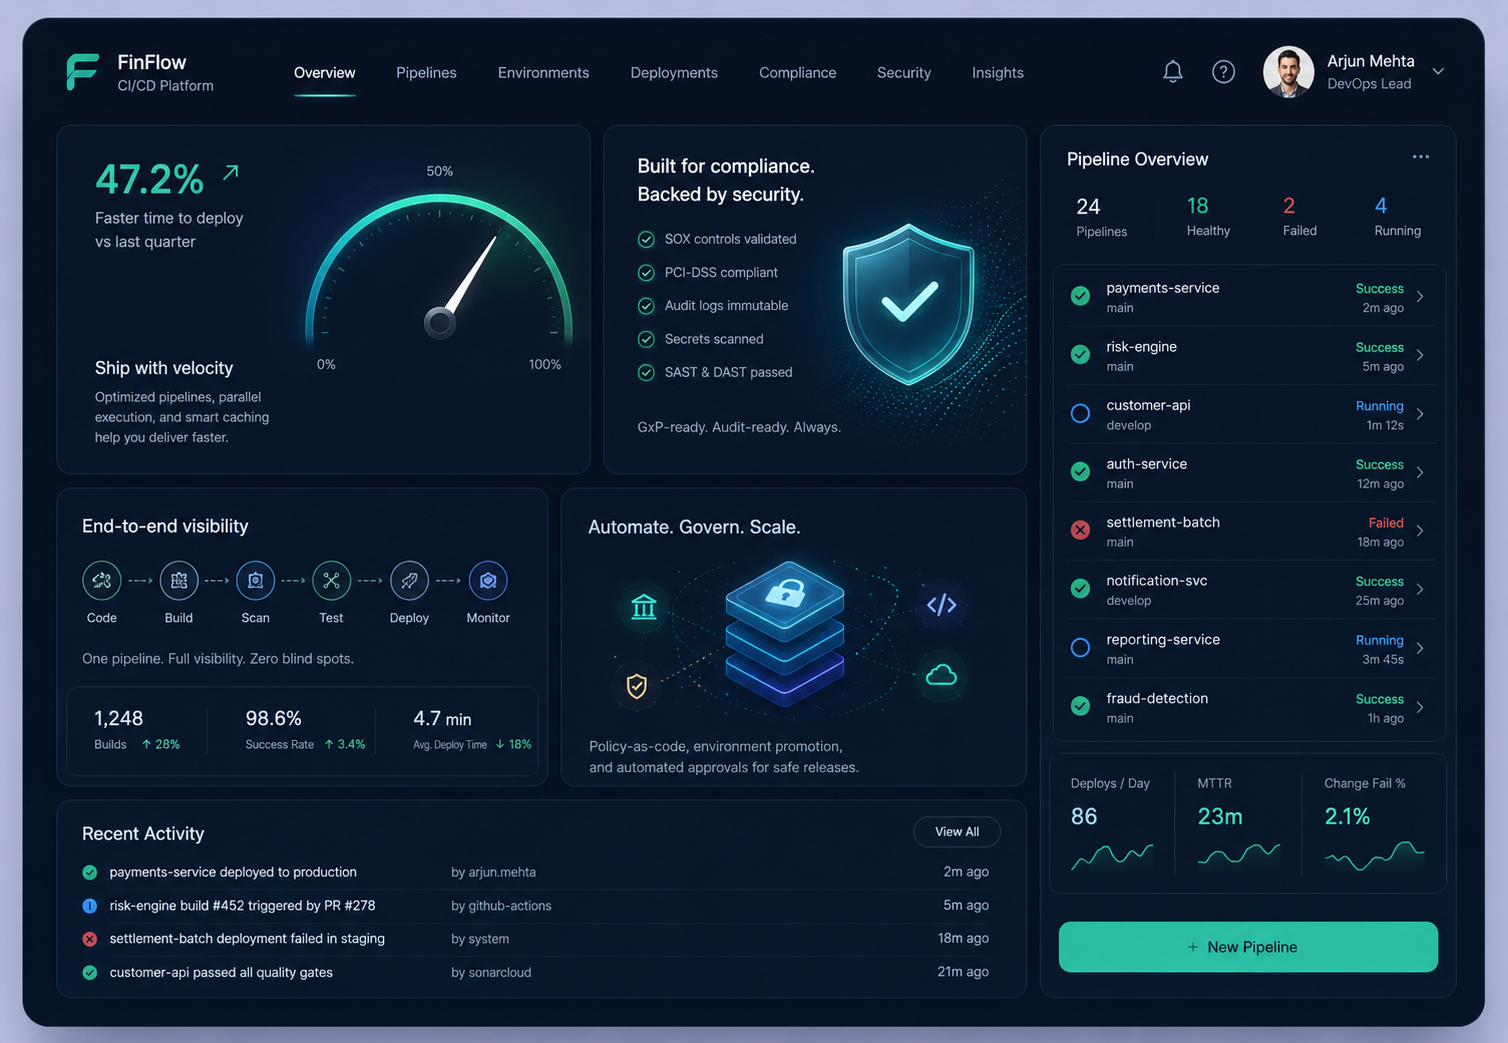
Lifted release frequency 15x with automated gates and one-click rollback.
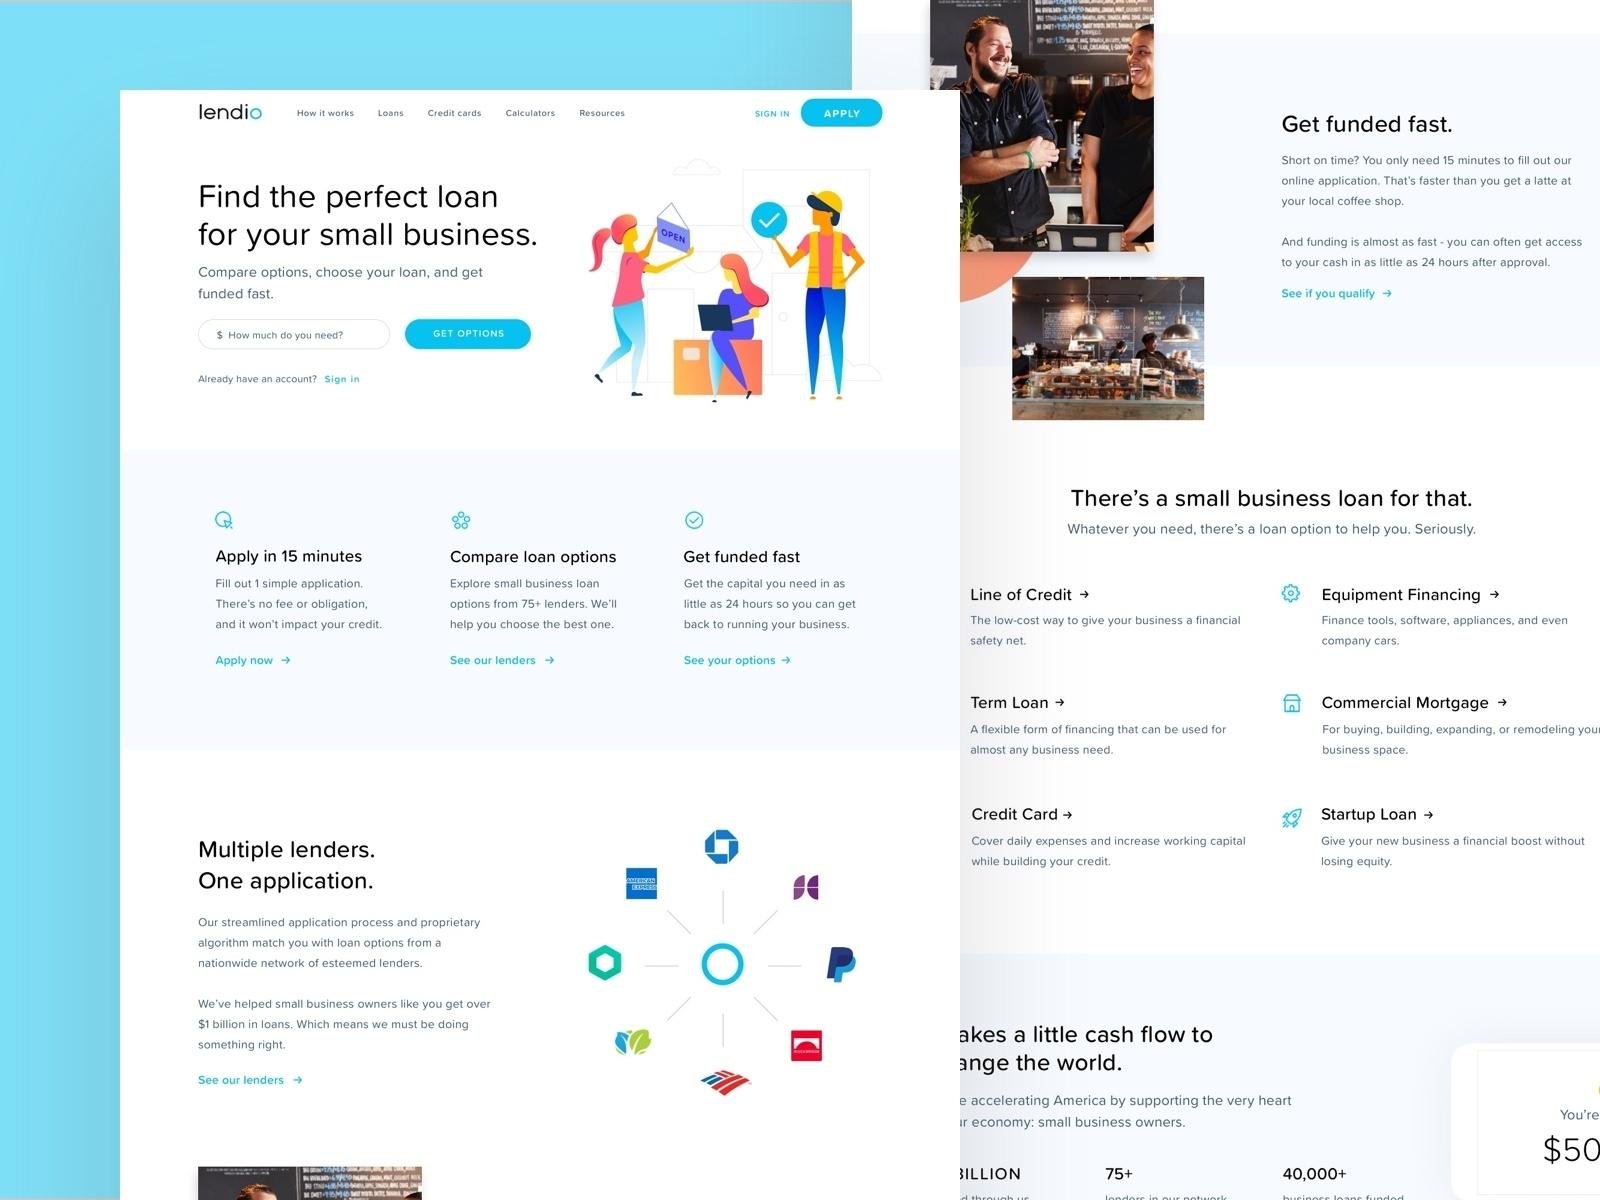
Matched borrower demand to non-custodial money markets through a single application, routing more than a billion dollars in loans across lines of credit and term loans.
Cut average handle time 44% across 2,600 agents, with answers grounded in approved policy only.
Resolved 89% of reconciliation breaks without a human, every action logged for audit.
Screened 12x more names at a lower false-positive rate, each hit evidenced.
Ledger, accounts, and payment rails delivered to an FCA launch milestone in 9 months.
Unified 120+ partner integrations behind one governed API gateway.
Straight-through KYC onboarding raised completion to 78%.
Re-platformed e-commerce to the cloud, holding availability through a record peak-season trading day.
Cut false-positive AML alerts 44% at a bank while catching more genuine risk.
Passwordless identity cut account-takeover 22% and sign-in friction at a wealth platform.
Delivered 10,000+ automated assertions across balance, transfer, and payment APIs, catching every schema and auth regression before release for a digital bank.
Isolated the true checkout bottleneck and produced a validated capacity model showing three times the throughput headroom the platform believed it had.
Tested login, SSO, and token flows end to end and hardened the identity layer against real abuse cases before rollout.
Scoped a focused credentialing pilot over a full rebuild, narrowing the programme 60% for a workforce management platform.
Delivered a reference architecture and a three-chain shortlist for embedding stablecoin settlement into a SaaS finance platform's cash-flow workflows.
Delivered a fractional real-estate tokenisation model with an ERC-3643 compliance blueprint for regulated investor onboarding.
Programmable escrow and stablecoin payout contracts cleared external audit with zero critical or high findings for a founder finance platform.
BritonOne Technology is a full-cycle engineering company that builds and operates production software for regulated estates. Since 2017, we have shipped programmes that clear audit on the first pass across banking, insurance, wealth, healthcare, and biotech. Our teams pair deep domain knowledge with disciplined engineering, treating compliance, security, and resilience as first-class deliverables. From architecture through to live operations, we stay accountable for the systems we build, measuring success by uptime, audit outcomes, and defensible business results.
Every quote below comes from a programme we shipped, and a reference our prospects are welcome to call.
“Our quote-to-fund cycle was nine days, auto-approval at 28%, underwriters drowning. BritonOne Technology shipped the new platform in twenty weeks. Quote-to-decision is now under 8 minutes and the PRA SS1/23 model-risk evidence cleared at first second-line review.”